Depth Charges: How Declining Ore Grades and Deeper Deposits Are Redrawing the Economics of North American Mining
The Ground Is Not Getting Any Easier
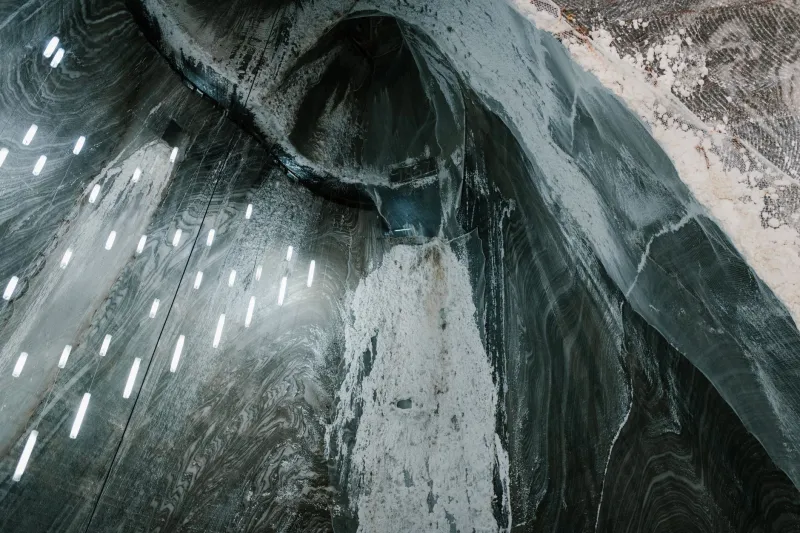
For much of the twentieth century, North American mining enjoyed a geological inheritance that made the industry look almost effortless in retrospect. High-grade deposits sat relatively close to the surface. Discovery costs were manageable. Ore bodies rewarded relatively straightforward extraction methods with healthy margins. That inheritance is largely spent.
Today, the industry confronts a convergence of geological realities that are fundamentally altering the cost structure of mineral extraction. Ore grades are declining across nearly every major commodity category. Copper deposits that averaged two percent or more in the mid-twentieth century now commonly run below half a percent. Gold mines that once processed ore at several grams per tonne are increasingly working with deposits measured in fractions of a gram. Meanwhile, the deposits that remain tend to be buried deeper, located in more complex geological formations, or situated in jurisdictions that carry their own operational complications.
For operators managing North American assets, these trends translate directly into margin pressure. The question is not whether these challenges will affect your operation—they almost certainly already are. The question is whether your organization is positioning itself to absorb and ultimately overcome them.
Why Discovery Is Becoming More Expensive
The mining industry's exploration productivity has declined measurably over the past several decades, even as exploration spending has increased substantially. The easy-to-find deposits were found first. What remains in underexplored regions tends to be concealed beneath cover rock, obscured by complex structural geology, or situated at depths that exceed the range of conventional prospecting methods.
The implications for reserve replacement are significant. A mine that processes ore at a rate of ten million tonnes per year must continuously replace those reserves or face an eventual production cliff. When near-surface, high-grade targets are scarce, operators must either drill deeper, explore in less-obvious geological settings, or acquire existing reserves through consolidation. All three paths carry costs that were largely absent from the industry's calculus a generation ago.
Exploration spending per discovered ounce—or per tonne of copper equivalent—has risen substantially even as major new discoveries have become rarer. The industry is not failing to look. It is running out of places where conventional looking produces results.
The Technology Response
The geological challenges driving this shift are real, but they are not insurmountable. The operators who will define the next decade of North American mining are those investing in exploration and processing technologies capable of doing what conventional methods cannot.
Geophysical surveying tools have advanced considerably. Airborne electromagnetic systems can now map conductive mineral bodies at depths that were effectively invisible to earlier generations of equipment. Gravity gradiometry and magnetotelluric surveys are helping exploration teams identify structural targets beneath thick cover sequences. Machine learning algorithms trained on legacy geological datasets are generating target recommendations that human interpreters might not have prioritized.
On the processing side, the response to declining ore grades has required equally significant innovation. When the ore feeding a mill contains less metal per tonne, the mill must either process more material—at greater cost—or recover a higher percentage of the metal present. Advances in flotation chemistry, sensor-based ore sorting, and fine grinding technology are allowing operators to extract value from material that earlier processing circuits would have sent to the tailings pond. These are not marginal improvements. In a low-grade environment, a two-percentage-point improvement in metallurgical recovery can be the difference between a viable operation and an uneconomic one.
Rethinking What Counts as an Ore Deposit
One of the more consequential shifts occurring across the industry is a fundamental reassessment of what qualifies as mineable. Deposits that were classified as subeconomic during periods of lower commodity prices or less sophisticated processing technology are being revisited with fresh eyes—and, in many cases, fresh economic models.
This reassessment is particularly relevant in the context of critical minerals. Deposits that contain cobalt, nickel, lithium, or rare earth elements alongside more conventional base metals are being evaluated not just for their primary commodity but for the combined value of everything they contain. Polymetallic deposits that might have been marginalized under a single-commodity economic framework are attracting renewed interest as operators develop the processing expertise to recover multiple revenue streams from a single ore body.
The practical implication is that reserve replacement, while genuinely challenging, is not exclusively a function of finding new deposits. It is also a function of finding new economic value in deposits that already exist—whether through improved processing, revised commodity price assumptions, or updated regulatory frameworks that expand what can be developed.
The Strategic Imperative for Operators
For mining companies operating in North America today, the geological horizon problem demands a response that is both tactical and strategic.
At the tactical level, operations must continuously evaluate whether their processing infrastructure is optimized for the ore grades they are actually processing—not the grades their predecessors designed for. Metallurgical testing programs, reagent optimization, and circuit audits are not glamorous investments, but in a low-grade environment they often generate returns that exploration drilling cannot match.
At the strategic level, reserve replacement must be treated as a core business function rather than a periodic exercise. Companies that maintain active exploration programs, cultivate relationships with junior exploration companies, and develop the internal technical capacity to evaluate acquisition targets will be better positioned to sustain production profiles as existing ore bodies mature.
The operators who thrive in the coming decade will be those who treat geological difficulty not as a complaint to register but as a competitive filter to exploit. When finding and processing ore becomes harder, the companies with superior technical capability, more sophisticated exploration programs, and more adaptable processing infrastructure will pull away from those that rely on methods developed for a geological environment that no longer exists.
The ground is harder to read than it used to be. The miners who learn to read it anyway will define what North American extraction looks like for the next generation.