Mined in America: The Strategic Race to Unlock Domestic Rare Earth Deposits Before the Next Crisis Arrives
There is a quiet irony embedded in the circuit board of nearly every smartphone sold in the United States. The device's vibration motor relies on neodymium. Its camera autofocus depends on dysprosium. The screen's luminescence is shaped by europium and terbium. These are not exotic curiosities—they are functional necessities. And for the better part of three decades, the overwhelming majority of them have come from a single foreign source: China.
For years, this arrangement was treated as an economic inevitability rather than a strategic vulnerability. Rare earth elements were cheap, Chinese processing infrastructure was mature, and domestic alternatives were viewed as financially uncompetitive. That calculus is now changing with considerable urgency.
What Makes Rare Earths Genuinely Irreplaceable
The term "rare earth elements" is something of a misnomer. The 17 elements classified under that designation—including lanthanum, cerium, praseodymium, and the heavier lanthanides—are not geologically scarce in absolute terms. Cerium, for example, is more abundant in the Earth's crust than copper. What makes them difficult is not their rarity but their dispersion. They rarely concentrate into economically viable ore bodies, and when they do, separating individual elements from one another requires sophisticated hydrometallurgical processes that are both capital-intensive and technically demanding.
This processing complexity is precisely why China came to dominate the sector. Beginning in the 1980s, Chinese state investment systematically built out extraction and separation capacity at a scale no private Western competitor could match on price alone. By the early 2000s, China controlled more than 90 percent of global rare earth production. That figure has moderated somewhat in recent years, but the processing chokehold remains intact. Even ore mined in other countries frequently travels to Chinese facilities for separation and refining.
The defense implications alone are significant. Rare earth permanent magnets are critical components in precision-guided munitions, radar systems, submarine propulsion, and the actuators that control aircraft flight surfaces. The Department of Defense has publicly acknowledged that the absence of a robust domestic rare earth supply chain constitutes a meaningful national security risk.
The American Geology Is More Promising Than the Headlines Suggest
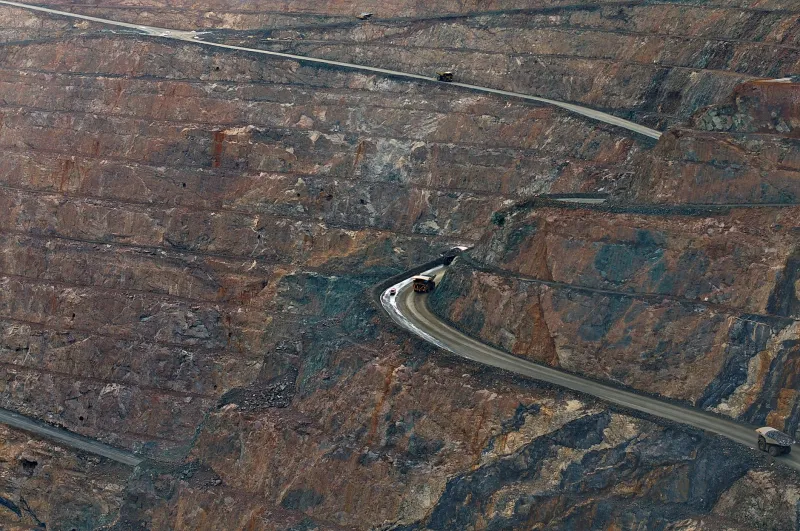
What is often underappreciated in public discussions is that the United States sits atop substantial rare earth reserves. The Mountain Pass mine in California's Mojave Desert was, for a period in the mid-twentieth century, the world's largest rare earth producer. The deposit remains one of the richest known concentrations of light rare earth elements on the planet. Operations there were curtailed in the 1990s and early 2000s due to a combination of environmental compliance costs and Chinese price competition—but the ore did not go anywhere.
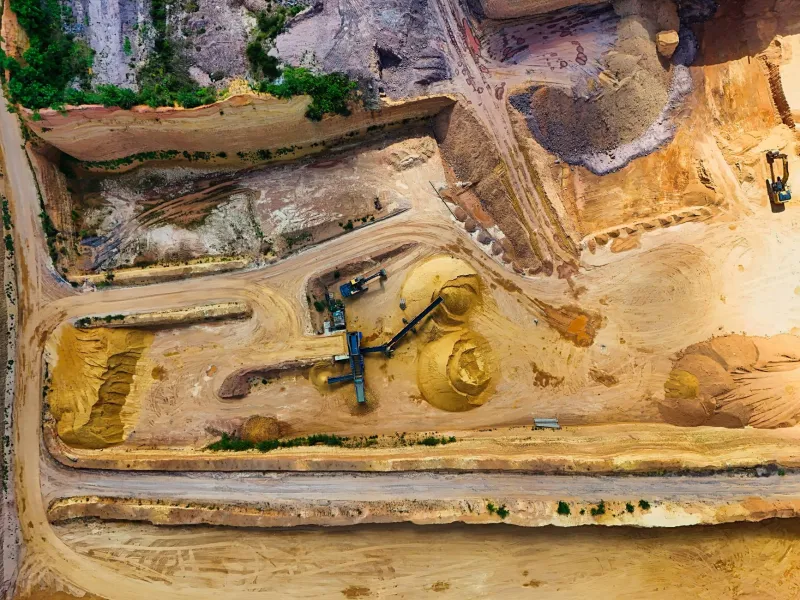
Beyond Mountain Pass, domestic geological surveys have identified promising deposits across Wyoming, Idaho, Montana, and the Colorado Plateau. Heavy rare earth concentrations—the category that includes the dysprosium and terbium most critical to high-performance magnets—have been documented in ionic clay formations in the southeastern United States, a deposit type previously associated almost exclusively with southern China.
Alaska's Bokan Mountain project represents another significant prospect, containing elevated concentrations of heavy rare earths in a deposit configuration that geologists consider technically workable. The challenge in nearly every case is not geological confidence—it is economic viability under current market conditions and the substantial permitting timeline that precedes any extraction activity.
The Technical Hurdles That Separate Discovery from Production
Identifying a deposit and extracting value from it are separated by a long and expensive interval. Rare earth projects face a distinctive set of technical challenges that distinguish them from conventional base metal mining.
First, rare earth ores are rarely dominated by a single element. A typical deposit will yield a mix of light and heavy rare earths in proportions that do not align neatly with market demand. Processing facilities must therefore manage a portfolio of co-products, some of which have limited commercial markets. This creates a revenue allocation problem that complicates project economics considerably.
Second, the separation chemistry involved in isolating individual rare earth oxides requires solvent extraction circuits of considerable complexity. Building a domestic separation facility capable of processing ore at commercial scale demands capital investment in the hundreds of millions of dollars, along with specialized technical expertise that the US workforce has not maintained at scale since the industry's earlier contraction.
Third, the radioactive thorium and uranium that occur naturally alongside many rare earth deposits create regulatory and waste management obligations that add cost and timeline to project development. Navigating these requirements within the existing permitting framework remains one of the industry's most persistent friction points.
Investment Is Following the Strategic Imperative
Despite these obstacles, the investment landscape has shifted materially in recent years. The combination of federal policy support—including provisions within the Defense Production Act, Department of Energy loan guarantees, and targeted funding through the Inflation Reduction Act—and genuine private sector urgency has begun to move projects from the feasibility stage toward construction.
Several domestic operators have secured offtake agreements with defense contractors and clean energy manufacturers who are actively seeking to de-risk their supply chains. This commercial pull is proving as important as policy push in making project economics work. When a magnet manufacturer or a wind turbine producer is willing to commit to a long-term purchase agreement at a defined price, it materially changes the financing calculus for a mine developer.
The rare earth magnet manufacturing sector itself is also beginning to re-emerge domestically, which matters because processing ore into refined oxides is only part of the value chain. Converting those oxides into the permanent magnets used in electric motors and generators requires additional industrial capacity that the US largely ceded over the past two decades. Rebuilding that capacity in parallel with upstream extraction is essential to achieving genuine supply chain independence rather than simply shifting one bottleneck for another.
A Long Game With Near-Term Stakes
Domestic rare earth development is not a problem that resolves itself in a single budget cycle or a single administration. The lead times involved in permitting, constructing, and commissioning a new mine and associated processing infrastructure are measured in years, sometimes in decades. That reality does not diminish the urgency—it amplifies it. Every year of delay in advancing viable domestic projects is another year of exposure to supply disruptions that are not hypothetical.
China has previously demonstrated a willingness to use rare earth export restrictions as a diplomatic instrument, most notably during a 2010 territorial dispute with Japan that sent prices for certain elements soaring by several hundred percent in a matter of months. The United States was not the direct target of that action, but the episode illustrated precisely how concentrated supply chains translate into concentrated leverage.
The geology beneath American soil has always held the raw materials needed to reduce that leverage. The question has never been whether the deposits exist—it has been whether the will, the capital, and the industrial infrastructure exist to bring them into production at the scale and pace the strategic moment demands. That question is now being answered, one project at a time, in the mountains and high desert of the American West.